A Cost Contribution Arrangement (CCA) is one of the common frameworks for MNEs to develop and exploit intangibles and services. The transfer pricing of CCAs is a complex topic that attracts considerable public attention. Both the OECD Guidelines and the UN Manual have separate chapters dedicated to CCAs. Also, some tax authorities have developed detailed guidance and regulations on CCAs that provide useful insight into their approach.
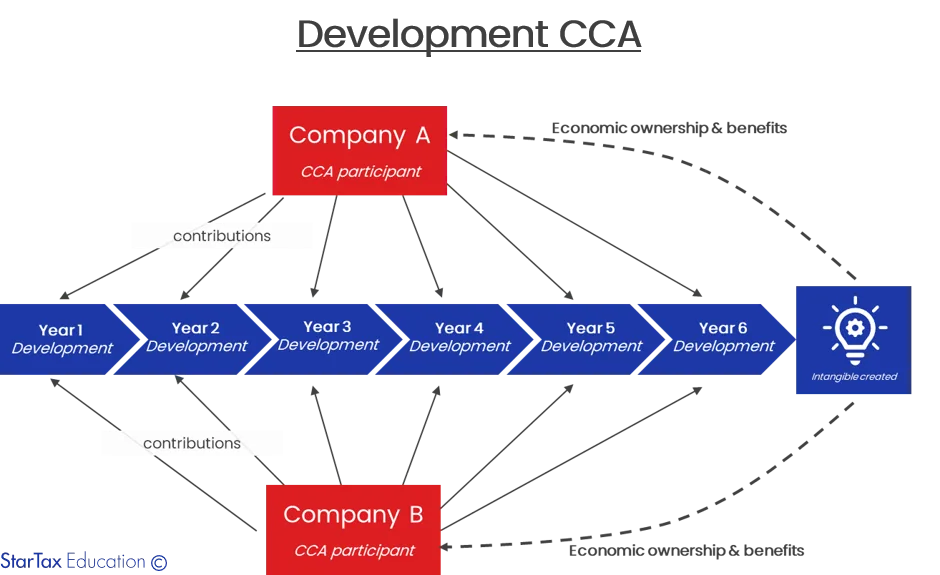
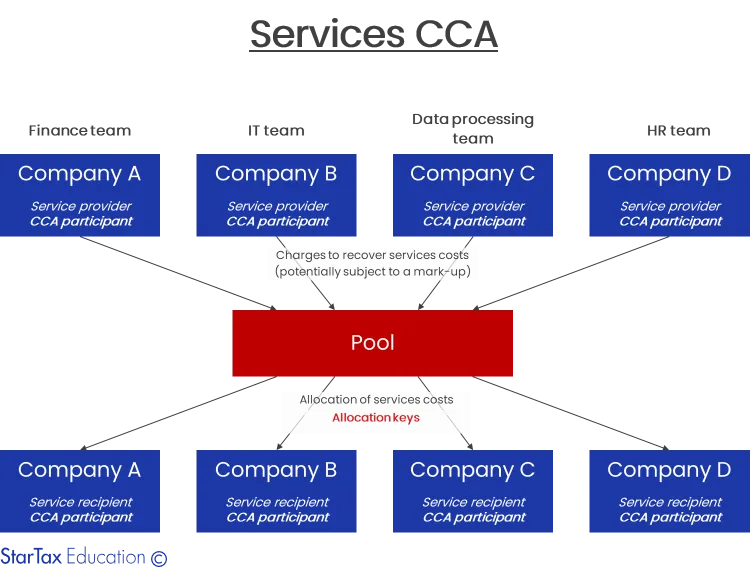
The idea of a CCA in international tax is broadly similar to a Cost-Sharing Arrangement (CSA) in the US. The major difference between two is that a CSA may be arranged only for joint IP development, whereas a CCA may be organised for joint IP development as well as service arrangements. In this chapter, we will focus on CCAs (not CSAs). Diagrams below illustrate development and services CCA models:
There are several key rules that every CCA should follow to be defensible from transfer pricing and tax perspective:
- A participant in a CCA should have the reasonable expectation that he will benefit from the objectives of the CCA activity itself (and not just from performing part or all of the activity within the CCA). Thus, for example, where a CCA is established with the objective of developing an intangible, a party that carries out research activities but is not assigned an interest in the intangible, will not be a participant within the CCA.
- A participant’s proportionate share of contributions to the CCA should be consistent with the proportionate share of expected benefits that the participant reasonably expects to receive.
- A CCA should have necessary balancing payments, buy-in and buy-out mechanisms in place.
- CCA documentation should be VERY strong. OECD Guidelines para. 8.52 provide the list of necessary information every taxpayer should maintain to defend his CCA, but you should also check your local recommendations and regulations (if they exist).
What are other CCA elements that are critically important from your perspective? Let us know, and we will add them to the list!In our textbook, we dedicate a detailed chapter for the discussion about CCAs, including 8 practical examples and cases that explain services and development CCAs.